 EN
Hurricane Claim Guide · By Tomas Robirosa, Esq.
Wind, rain, flooding and fallen trees can all damage a Florida home. Here is what a typical homeowners policy covers, how the hurricane deductible works, and the steps that help protect your claim.
Tropical Storm Isaias formed in the Gulf on October 7, 2026 and was forecast to become the first hurricane of the season, and Florida declared a state of emergency for 25 counties. In South Florida, heavy downpours and king tides brought the risk of localized flooding the same week. If a storm damages your home, a hurricane damage insurance claim is usually how repairs get paid for, and the first weeks matter. This guide explains the basics under Florida law. This article is general information, not legal advice.
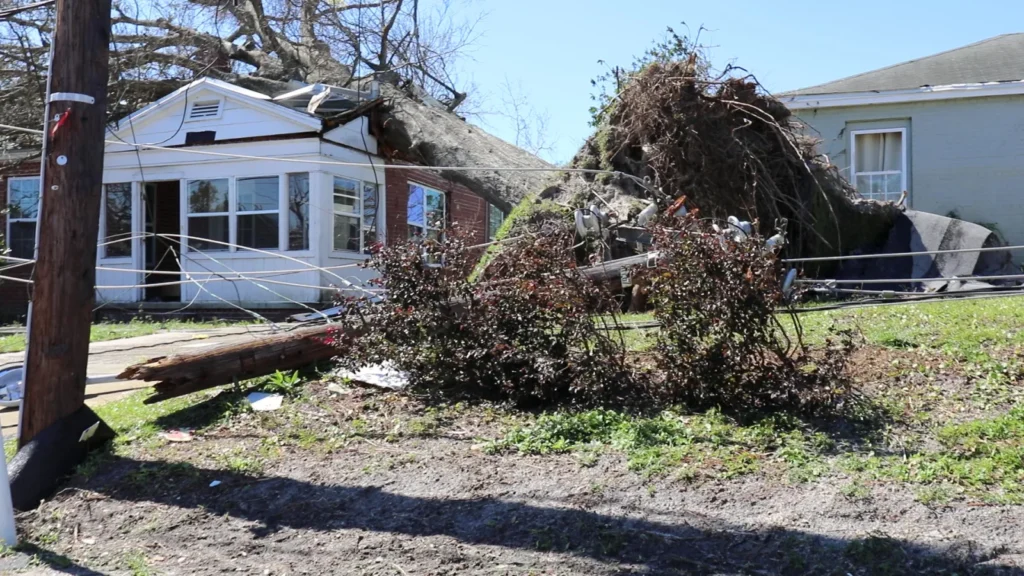
Usually, a standard homeowners policy covers damage caused by wind: a torn-off roof, broken windows, a fallen tree that hits the house, and rain that gets in through an opening the wind created. Coverage always depends on the exact wording of your policy, its exclusions and your deductible.
Flood is different. Most homeowners policies do not cover flood damage, meaning rising water from storm surge, overflowing canals, king tides or heavy rain that pools and enters the home. Flood damage is usually covered only by a separate flood policy, either through the National Flood Insurance Program (NFIP) or a private flood insurer. New flood policies usually have a waiting period before they take effect, so buying one when a storm is already on the way may not help with that storm.
After a hurricane, insurers often argue about whether damage was caused by wind (covered) or by flood (excluded). Photos taken before and right after the storm, and an inspection of where the water entered, can make a big difference. If water got in through a damaged roof or a leaking pipe, see our page on water damage claims.
In a condominium, the association's policy and your own unit-owner (HO-6) policy may each cover different parts of the damage. If the association and the owner disagree about who pays, see our condominium disputes page.
Florida policies usually have a separate hurricane deductible. Under section 627.701, Florida Statutes, insurers must generally offer hurricane deductible options of $500, 2 percent, 5 percent and 10 percent of the dwelling limit, with some exceptions for higher-value homes. A 2 percent deductible on a home insured for $400,000, for example, is $8,000.
Under section 627.70132, Florida Statutes, notice of a new or reopened property insurance claim must generally be given within 1 year after the date of loss, and notice of a supplemental claim generally within 18 months. Every case is different, so speak with an attorney to confirm the deadline that applies to you.
For a hurricane or other weather event, the same statute says the date of loss is generally the date of landfall or the date the event is verified by the National Oceanic and Atmospheric Administration. Every case is different, so speak with an attorney to confirm the deadline that applies to you.
Even so, reporting quickly is usually better. Damage gets harder to prove as time passes, repairs cover up evidence, and mold or leaks can spread.
Florida law gives homeowners specific protections during a claim. Under section 627.7142, Florida Statutes, an insurer that writes residential property policies must send you the Homeowner Claims Bill of Rights after you report a claim. Among other things, it explains these rules from section 627.70131, Florida Statutes:
Denials and low offers are common after major storms. Common reasons include the insurer saying the damage was caused by flood rather than wind, that the roof damage was old wear and tear, that the damage is below the deductible, or that the claim was reported too late.
Options can include asking the insurer to explain the decision in writing, sending more photos and estimates, requesting state mediation, or using the appraisal process if your policy has one. Before a lawsuit, Florida law also generally requires a written notice of intent to initiate litigation under section 627.70152, Florida Statutes, sent at least 10 business days before the suit is filed. Every case is different, so speak with an attorney to confirm the deadline that applies to you.
A denial letter is not always the final word. Tomas Robirosa helps Florida homeowners and condo owners with hurricane damage claims and denied or underpaid insurance claims, in English and Spanish. The consultation is free, and there is no fee unless we recover.
Photo: M. Amaya / VOA, Wikimedia Commons, public domain
This article is for general information only and is not legal advice. Every situation is different, and the law can change. Do not make decisions based on this article alone. Speak with a licensed Florida attorney about your specific situation. Reading this article does not create an attorney-client relationship.
Prefer to talk to a lawyer now?
Call (305) 600-0529Se habla español · Available 24/7
Your Attorney
Tomas Robirosa is the founding attorney of Robirosa Accident & Injury Law. He built his practice around careful preparation and personal attention: when you hire the firm, you talk to your lawyer, in English or Spanish, and you always know where your case stands.
He graduated cum laude from Nova Southeastern University’s Shepard Broad College of Law, is a Florida Supreme Court Certified Circuit Civil Mediator, and is admitted to practice in Florida state courts and the U.S. District Court for the Southern District of Florida.
Recognition & memberships
Real reviews from real clients on Google.
EXCELLENT Based on 36 reviews
 Posted on Google

 Maša NestorovićI’ve had an amazing experience working with Tomas. He is super knowledgeable and very personable. He helped us tremendously, highly recommend.Posted on Google
 Kathy Maria AlvarezTomás fue un excelente profesional.Me dejó muy tranquila porque me explicó todo en español, con total claridad y transparencia. Si tuviste un accidente en Miami Beach, no dudes en llamarlo.Posted on Google
 Cristina GonzalezThe absolute best!! Responsive, honest, and easy to talk to. If you need an injury attorney in Miami Beach who also speaks Spanish, Tomas is the one to call. Highly recommend having him handle your case.Posted on Google
 Mario EspinosaAs a physical therapist, I’ve had the opportunity to work with Robirosa Accident & Injury Law while treating patients recovering from injuries. Their team has always been professional, responsive, and genuinely focused on making sure their clients receive the care they need. From a healthcare provider’s perspective, communication and coordination can make a huge difference in these cases, and their team does a great job staying involved without interfering with the clinical process. It’s clear they care about their clients as people, not just as cases. I would highly recommend Robirosa Accident & Injury Law to anyone looking for an injury attorney who is professional, accessible, and committed to helping their clients through the recovery process.Posted on Google
 Derek NierTomas is an industry professional. He handles his cases with extreme care and provides excellent customer service alongside excellent communication. I would recommend him to anyone looking for a competent attorney in the Miami Beach area.Posted on Google
 Rosalia Rodriguez AquinoEs muy buen Abogado, confiable, transparente y muy humanitario. Estás siempre pendiente a todos y muy comunicativo. Me siento muy satisfactoria de su buen trabajo. Ojalá hayan muchos abogados como él. Que Dios lo bendiga Gracias, porque ganamos el casoPosted on Google
 Andrea Silva🌟🌟🌟🌟🌟 Wow- excelente experiencia con Tomás. Lo recomiendo al 100%. Cuando ningún otro abogado me apoyaba y sentía que el caso estaba perdido, me conectaron con él y ¡ganamos! El proceso fue claro, fluido y efectivo. Es muy profesional, sabe exactamente lo que hace y realmente le importa ayudar a sus clientes. Estoy muy agradecida por su apoyo y sin duda lo recomendaré a cualquier persona que necesite un abogado.Posted on Google
 Karim BadawyThomas is a true professional! He is knowledgeable and will provide everything he knows for you! Highly recommend!Posted on Google
 Evelynorteganavarro1211 OrtegaLo súper recomiendo, una persona muy profesional, honesta. Me ayudó a mí con la solución de un caso, todo salió súper bien,sin duda alguna el mejor..Posted on Google
 Claudn TattooThe best of the best! Currently helping me through my case. Thomas has literally taken away all the stress from this court case
Tell us what happened. We’ll explain your options in English or Spanish, with no obligation.