Free Consultation — Talk to a Florida Lawyer TodayNo fee unless we recoverHablamos españolAvailable 24/7
5.0Google Reviews
CALL 24/7(305) 600-0529WhatsApp UsText us now, tap to chat
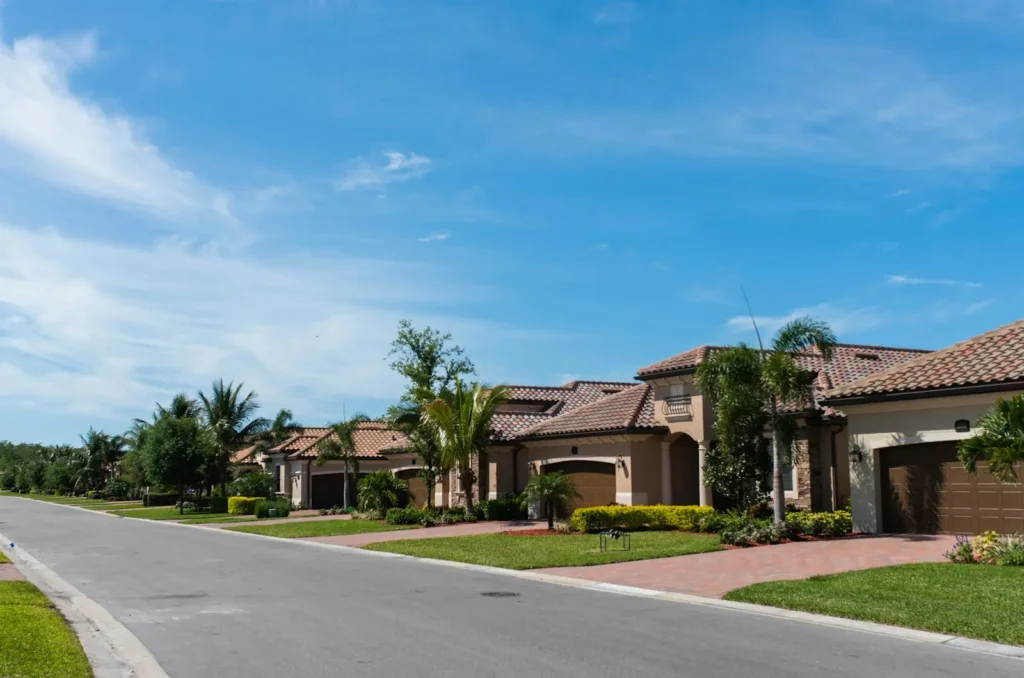
Homes on a residential street in South Florida

Miami-Dade · Broward · Palm Beach

Denied Property Insurance Claim Lawyer in Miami

Did Your Insurance Company Deny, Delay, or Underpay Your Property Damage Claim?

  • Free consultation
  • No attorney’s fee unless we recover
  • Hablamos español
  • Available 24/7
Photo: FilterGrade / Unsplash
  • Free ConsultationNo cost, no obligation
  • No Fee Unless We RecoverContingency fee cases
  • Bilingual AttorneyEnglish & Spanish
  • Available 24/7Fast communication

You paid your premiums so your insurer would be there when you needed it. When a property damage claim is denied, delayed or paid for far less than the repairs cost, it can feel like you have nowhere to turn. Denied insurance claim lawyer Tomas Robirosa helps Florida homeowners and condo owners read the denial, understand their policy and challenge the decision. He serves clients across Florida, with a focus on Miami-Dade, Broward and Palm Beach counties. Se habla español.

Common Reasons Property Claims Are Denied

  • Policy exclusionssuch as flood, wear and tear, deterioration, mold, or long-term leakage
  • Late noticeof the claim
  • Disputes about the cause of loss, such as wind vs. flood, or sudden leak vs. long-term seepage
  • Pre-existing damagearguments, especially on older roofs
  • Alleged failure to mitigate, meaning the insurer claims you did not take reasonable steps to prevent further damage
  • Alleged misrepresentationor incomplete documentation
  • Low estimatesthat leave out damaged areas, matching, code upgrades, or tear-out costs

What to do after a denial or lowball offer

  • Ask for the denial or payment explanation in writing.
  • Request a certified copy of your complete policy, including endorsements.
  • Keep every photo, video, invoice, estimate, and letter.
  • Do not throw away damaged materials without documenting them.
  • Write down the names of adjusters and the dates of every inspection and call.
  • Do not sign a release or cash a check marked "final payment" until you understand what you are giving up.

How We Challenge Denied and Underpaid Claims

We start by reading your policy and the insurer's stated reasons line by line. Then we compare the insurer's estimate with the actual damage and identify what was missed.

Reading your insurance denial letter

An insurance denial letter should tell you which part of the policy the insurer is relying on. Florida’s unfair claim settlement practices law (section 626.9541, Florida Statutes) lists failing to promptly provide a reasonable written explanation of the policy basis for denying a claim as an unfair claim practice. When we review an insurance denial, we look at:

  • The exact policy language the insurer cites, and whether an endorsement changes it
  • Whether the denial is full or partial, and what was left out of the estimate
  • What evidence the insurer relied on, such as the field adjuster’s or an engineer’s report
  • Whether the insurer met Florida’s claim-handling deadlines

Florida rules that apply to your claim

  • Reporting deadlinesA new or reopened claim generally must be reported within one year after the date of loss, and a supplemental claim within 18 months. Every case is different, so speak with an attorney to confirm the deadline that applies to you.
  • Insurer deadlinesInsurers generally must acknowledge a claim within 7 days, physically inspect within 30 days of proof of loss, and pay or deny within 60 days after notice of the claim, subject to limited exceptions.
  • Pre-suit noticeBefore filing suit, the policyholder must generally give at least 10 business days' written notice of intent to sue, with an itemized demand.
  • Lawsuit deadlineA suit for breach of a property insurance contract generally must be filed within five years from the date of loss. Every case is different, so speak with an attorney to confirm the deadline that applies to you.

Options to resolve your claim

  • Supplemental claims with additional documentation
  • Reinspection and negotiation with the insurer
  • Appraisal, when the policy includes an appraisal clause
  • Mediation programs available for certain residential claims
  • Litigation, when the insurer will not pay what the policy owes

Types of property claims we handle

Hurricane and windstorm damage, water damage from plumbing leaks, leaking pipes, window leaks and sewage backup, roof damage, fire and smoke damage, and condominium claims.

Request a free review of your denied or underpaid claim.

Florida Law at a Glance
  • Report the claim promptly: under current Florida law, a new or reopened property insurance claim generally must be reported within one year after the date of loss, and a supplemental claim within 18 months. Every case is different, so speak with an attorney to confirm the deadline that applies to you.
  • Insurer deadlines: Florida law generally requires the insurer to pay or deny the claim within 60 days after receiving notice, unless factors beyond its control prevent it.

When insurance companies refuse to pay, the reason they give is not always the full story. Some insurers deny your claim citing a policy exclusion or missing documents; others underpay to avoid paying the full cost of repairs after natural disasters like hurricanes and tropical storms. If you believe your claim was wrongfully denied, an insurance claims lawyer can review the denial letter, your policy and the adjuster's estimate and explain whether legal action makes sense. In some cases, Florida law allows a separate claim when an insurer acted in bad faith, but bad faith insurance claims and challenges to other bad faith practices have their own requirements, and every case is different. Our law firm can walk you through the insurance dispute and your options, so speak with an insurance claims attorney before accepting a final denial.

How We Handle Property Damage Claims

  • Step 1Free claim reviewWe review your policy, your claim, and every letter from the insurance company, in English or Spanish.
  • Step 2Documenting the damageWe gather photos, repair estimates, and independent inspections to show the full cost of the loss.
  • Step 3Challenging the decisionWe respond to delays, underpayments, and denials, and send any pre-suit notice Florida law requires.
  • Step 4Lawsuit if neededIf the insurer or association will not treat you fairly, we are prepared to take the case to court.

Florida's Pre-Suit Notice: What It Must Include and What Happens Next

If your property damage claim was denied in Florida, you generally cannot go straight to court. Section 627.70152 of the Florida Statutes makes a written notice of intent to initiate litigation a condition before suing under a residential or commercial property policy. In general:

  1. The insurer decides first. The notice may not be given before the insurer has made a coverage decision on the claim.
  2. The notice is filed with the state. It is filed through the Florida Department of Financial Services, which sends it to the insurer, generally at least 10 business days before a lawsuit is filed.
  3. It must say what is wrong. The notice must state the insurer's acts or omissions that are in dispute. After a coverage denial, it includes an estimate of damages, if known. After other problems, such as an underpayment, it includes an itemized pre-suit settlement demand and the disputed amount.
  4. The insurer must answer. The insurer generally must respond in writing within 10 business days. After a denial, it may accept coverage, keep denying, or ask to reinspect, which gives it 14 business days to decide. After other disputes, it must make a settlement offer or require appraisal or another form of alternative dispute resolution.
  5. Skipping it has a cost. A lawsuit filed without the required notice, or before the waiting period ends, must be dismissed without prejudice, which can cost you time.

Because the notice shapes what comes next, it is worth getting the estimate and the disputed amount right. We prepare the notice, track the insurer's response and advise you on each option. Every case is different, so speak with an attorney to confirm the deadline that applies to you.

Property Damage Claim Denied in Florida? Your Options After the 2022 Reforms

Florida's 2022 property insurance law (SB 2-A) and its 2023 civil law changes (HB 837) changed the math of fighting a denial. Before those laws, a policyholder who won a lawsuit against a property insurer could often ask the court to order the insurer to pay the policyholder's attorney fees. Those one-way fee rules no longer apply to property insurance lawsuits. SB 2-A also made offers of judgment available again in these suits, which can affect who pays certain fees and costs if a case goes to trial.

That doesn't mean a denied claim is a lost cause. It means you should understand your options, and their risks, before choosing one:

  • Supplemental claim or reinspection Sometimes new photos, a contractor's report or an engineer's opinion is enough for the insurer to change its decision.
  • Appraisal If your policy has an appraisal clause and the dispute is about the amount of loss, appraisal may resolve it without a lawsuit.
  • Mediation Florida offers a mediation program for many residential property claims.
  • Lawsuit If the insurer won't be fair, a lawsuit after pre-suit notice may be the right step. A lawsuit for breach of a property insurance contract has its own deadline, generally measured from the date of loss. Every case is different, so speak with an attorney to confirm the deadline that applies to you.

We review the denial, your policy and the evidence, and we explain each path in plain language, in English or Spanish. We work on a contingency basis: no fee unless we recover, and we explain how fees and costs work before you decide to hire us. Call (305) 600-0529 for a free claim review, or read about hurricane damage and water damage claims.

In Miami Beach? See our Miami Beach denied insurance claim lawyer page.

Frequently Asked Questions

What can I do if my property insurance claim is denied in Florida?
Start by getting the denial in writing and a certified copy of your policy. A lawyer can review whether the denial is supported by the policy, help gather additional evidence, request reconsideration, pursue appraisal if the policy provides for it, and, if necessary, file suit after giving Florida's required pre-suit notice.
How long do I have to sue my insurance company in Florida?
Florida's statute of limitations for a lawsuit for breach of a property insurance contract is generally five years from the date of loss, but separate deadlines to report the claim are much shorter: generally one year for a new claim and 18 months for a supplemental claim. Every case is different, so speak with an attorney to confirm the deadline that applies to you.
What is pre-suit notice?
Before suing a property insurer, Florida law generally requires the policyholder to give written notice of intent to sue at least 10 business days in advance, including an itemized settlement demand. The insurer then has an opportunity to respond.
What if my claim was underpaid instead of denied?
An underpaid claim can be disputed much like a denial. Common issues include estimates that leave out damaged areas, code upgrades, or hidden damage.
Do I need a lawyer for an insurance denial in Miami?
Not always. Some denials are resolved by sending missing documents or a supplemental claim. But if the insurer cites an exclusion, disputes the cause of the damage, or pays far less than your contractor’s estimate, a lawyer can review the denial letter and your policy and explain your options, including appraisal if your policy has an appraisal clause, or a lawsuit after Florida’s required pre-suit notice. Every case is different, so speak with an attorney about yours.
What changed for Florida homeowners who sue their insurer after 2022?
Florida's 2022 and 2023 laws ended one-way attorney fees in property insurance lawsuits, so a homeowner should not expect the insurer to be ordered to pay the homeowner's attorney fees just because the homeowner wins. The laws also generally require written pre-suit notice at least 10 business days before filing suit. Every case is different, so speak with an attorney to confirm the deadline that applies to you.
What happens if I file a lawsuit without pre-suit notice?
Under section 627.70152, a court must dismiss without prejudice a property insurance lawsuit filed without the required notice or before the waiting period ends. The case can usually be refiled, but you lose time.
Can the insurer reinspect my home after I send pre-suit notice?
Yes, in some cases. After a coverage denial, the insurer may respond by asserting a right to reinspect the property. It then generally has 14 business days to accept coverage or continue to deny.

Free Consultation!

Prefer to talk to a lawyer now?

Call (305) 600-0529Se habla español · Available 24/7
Tomas Robirosa
Tomas Robirosa, Esq.Founding Attorney
Florida Supreme Court Certified Circuit Civil Mediator
Tomas Robirosa, Miami personal injury lawyer

Your Attorney

Work Directly With Attorney Tomas Robirosa

Tomas Robirosa is the founding attorney of Robirosa Accident & Injury Law. He built his practice around careful preparation and personal attention: when you hire the firm, you talk to your lawyer, in English or Spanish, and you always know where your case stands.

He graduated cum laude from Nova Southeastern University’s Shepard Broad College of Law, is a Florida Supreme Court Certified Circuit Civil Mediator, and is admitted to practice in Florida state courts and the U.S. District Court for the Southern District of Florida.

  • Licensed in Florida
  • Bilingual: English & Spanish
  • Certified Circuit Civil Mediator
  • U.S. District Court, S.D. Florida
  • Free consultations
  • Contingency fee: no fee unless we recover

Recognition & memberships

Elite Lawyer Personal Injury 2026 badgeLawyers of Distinction 2026 badgeAIOTL 40 Under 40 2026 badgeFlorida Justice Association badgeThe Florida Bar Trial Lawyers Section logoAvvo Clients' Choice Award 2026 badge, Tomas RobirosaAvvo client reviews badge, Tomas Robirosa

What Our Clients Say

Real reviews from real clients on Google.

Posted on Google Google
Kk Ll profile picture
Kk Ll
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Great service would recommend helped tremendously
Posted on Google Google
Johanna Martinez profile picture
Johanna Martinez
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
LA ATENCION FUE EXCELENTE Y MUY RAPIDA.
Posted on Google Google
Maša Nestorović profile picture
Maša Nestorović
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I’ve had an amazing experience working with Tomas. He is super knowledgeable and very personable. He helped us tremendously, highly recommend.
Posted on Google Google
Kathy Maria Alvarez profile picture
Kathy Maria Alvarez
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Tomás fue un excelente profesional.Me dejó muy tranquila porque me explicó todo en español, con total claridad y transparencia. Si tuviste un accidente en Miami Beach, no dudes en llamarlo.
Posted on Google Google
Cristina Gonzalez profile picture
Cristina Gonzalez
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
The absolute best!! Responsive, honest, and easy to talk to. If you need an injury attorney in Miami Beach who also speaks Spanish, Tomas is the one to call. Highly recommend having him handle your case.
Posted on Google Google
Mario Espinosa profile picture
Mario Espinosa
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
As a physical therapist, I’ve had the opportunity to work with Robirosa Accident & Injury Law while treating patients recovering from injuries. Their team has always been professional, responsive, and genuinely focused on making sure their clients receive the care they need. From a healthcare provider’s perspective, communication and coordination can make a huge difference in these cases, and their team does a great job staying involved without interfering with the clinical process. It’s clear they care about their clients as people, not just as cases. I would highly recommend Robirosa Accident & Injury Law to anyone looking for an injury attorney who is professional, accessible, and committed to helping their clients through the recovery process.
Posted on Google Google
Derek Nier profile picture
Derek Nier
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Tomas is an industry professional. He handles his cases with extreme care and provides excellent customer service alongside excellent communication. I would recommend him to anyone looking for a competent attorney in the Miami Beach area.
Posted on Google Google
Rosalia Rodriguez Aquino profile picture
Rosalia Rodriguez Aquino
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Es muy buen Abogado, confiable, transparente y muy humanitario. Estás siempre pendiente a todos y muy comunicativo. Me siento muy satisfactoria de su buen trabajo. Ojalá hayan muchos abogados como él. Que Dios lo bendiga Gracias, porque ganamos el caso
Posted on Google Google
Andrea Silva profile picture
Andrea Silva
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
🌟🌟🌟🌟🌟 Wow- excelente experiencia con Tomás. Lo recomiendo al 100%. Cuando ningún otro abogado me apoyaba y sentía que el caso estaba perdido, me conectaron con él y ¡ganamos! El proceso fue claro, fluido y efectivo. Es muy profesional, sabe exactamente lo que hace y realmente le importa ayudar a sus clientes. Estoy muy agradecida por su apoyo y sin duda lo recomendaré a cualquier persona que necesite un abogado.
Posted on Google Google
Karim Badawy profile picture
Karim Badawy
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Thomas is a true professional! He is knowledgeable and will provide everything he knows for you! Highly recommend!